Chapter 9
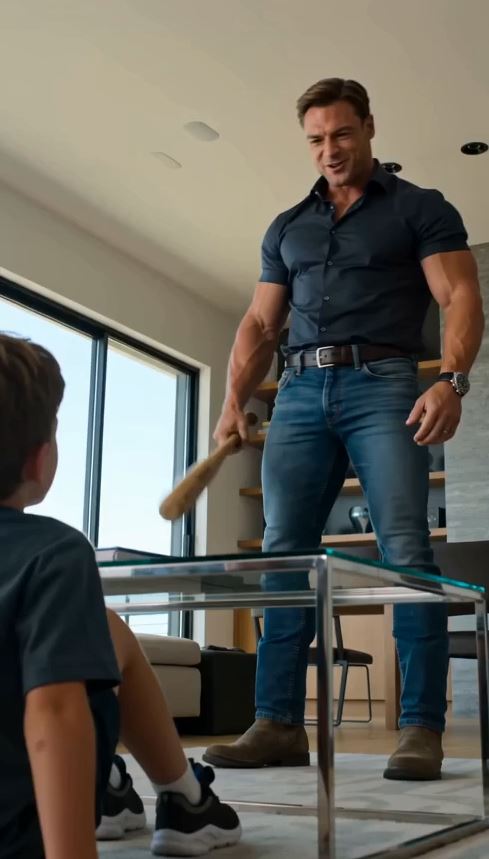
The independent fiduciary did something Rhydian might not have done.
It negotiated.
Instead of immediately suing Ulric over the buy-sell exercise, the fiduciary demanded complete disclosure from Blackridge, Northwell, Ulric, Calder’s estate records, and the company’s outside accountants.
Ulric refused part of it.
The fiduciary filed suit.
Then discovery revealed a side agreement nobody had seen.
Blackridge and Ulric had signed it twelve days before the baseball-bat incident.
Not after Calder’s death generally.
Not months earlier.
Twelve days before Ulric smashed the table beside Esmond.
The agreement was titled:
Transaction Cooperation Framework.
Ulric committed to use “commercially reasonable efforts” to consolidate at least ninety-four percent ownership of Northwell before a proposed sale.
Blackridge committed to fund a portion of the acquisition price for Calder’s shares through an escrowed loan to Ulric.
Amount available:
$3.5 million.
Enough to exercise the low-value buyout.
Rhydian stared at the figure.
“Blackridge was going to lend him the money to buy Esmond’s shares.”
The fiduciary’s attorney nodded.
Then:
“After which Blackridge would buy nearly all the company.”
The circularity was obvious.
But the side agreement alone still did not prove fraud.
Private equity routinely financed management rollover transactions.
The key issue remained disclosure.
Ulric had not told Calder’s estate that the same third-party buyer whose offer should potentially reset the buyout price was financing Ulric’s exercise of the low-price option.
Then came an email.
Blackridge lawyer:
Need comfort estate option process is clean. If 11.4 applies, price exposure changes materially.
Ulric:
11.4 doesn’t apply. Calder rejected Blackridge while alive.
Lawyer:
Current proposal exists post-death. Estate counsel may view “received” differently. Recommend disclosure.
Ulric:
No. Disclosure lets Rhydian blow up guardianship and drag this out.
The lawyer replied:
Guardianship should not be relevant to corporate disclosure.
Ulric never answered.
Another email:
Need close before court gives R control of kid matters.
The business case and guardianship case had intersected inside Ulric’s own writing.
Still, investigators wanted to know why.
Rhydian no longer controlled company decisions.
The bank trustee did.
Why care who raised Esmond?
Then the fiduciary found a provision in Calder’s trust.
Not financial authority.
Information.
Once Rhydian became permanent guardian, he was entitled to receive annual trust reports on Esmond’s behalf and petition for special accountings if he suspected waste.
He could not direct investments.
Could not force a company sale.
But he could see.
That was enough.
Ulric had spent seven weeks trying to keep the one adult Calder trusted most from gaining a legally recognized position from which he could ask questions.
The bat incident was not staged for a hearing.
Ulric had not planned Rhydian’s arrival.
He did not know Esmond would use the emergency phone.
The violence was simpler.
Esmond refused to tell him where Calder’s records were.
Ulric lost his temper.
Then threatened a child exactly the way he threatened adults:
Make enough noise.
Break something expensive.
Let fear finish the conversation.
What Ulric failed to understand was that Calder had prepared Esmond for one specific moment.
May you like



Not with corporate documents.
With one phone number.







