Chapter 9
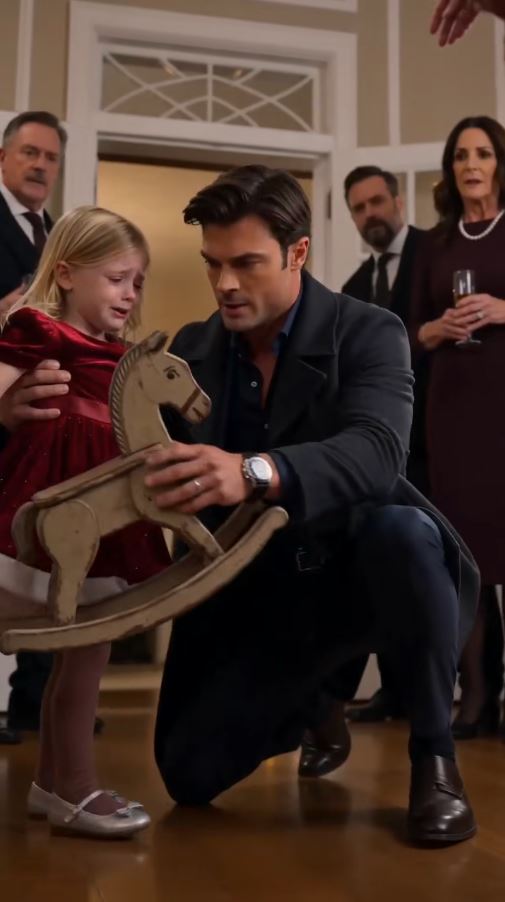
The independent administrator paused the Alder Crown closing.
Not canceled.
Paused.
Alder Crown protested immediately.
It had spent millions on diligence and financing arrangements.
Its executives had no interest in becoming characters in a family feud.
So they asked a sensible question.
“What exactly did we buy?”
The answer was suddenly unclear.
Their $92 million equity valuation assumed Vale Heritage did not own the sixteen Edmund Collection designs.
It assumed a long-term license from Northstar.
It assumed no undisclosed related-party conflict affecting that arrangement.
And it assumed the seller’s conflict disclosures were accurate.
Northstar’s economics changed those assumptions.
Then the audit found Sophronia’s sale-side incentive.
Aster Grove had granted her management vehicle a post-change-of-control option.
If Alder Crown bought Vale, Sophronia could increase her Northstar interest from thirty-four to forty-nine percent for a fixed exercise price of $1.8 million.
Based on projected licensing cash flow, independent bankers estimated the option might be worth between $4.5 million and $6.5 million immediately after closing.
That was separate from what Sophronia received through Edmund’s estate.
Separate from her personal Vale shares.
Separate from executive compensation.
She stood to make more if the designs remained outside the company.
The buyer had not been told.
Neither had Edmund.
Then one of the board directors admitted something.
Paul Raines had voted for the Northstar transfer because Sophronia told him Edmund supported it and wanted the company “simplified for succession.”
He never saw the earlier appraisal.
He never knew Sophronia owned management equity.
Would he have voted differently?
“Yes.”
Melissa Ford said the same.
That created serious fiduciary issues.
Then the audit reconstructed Vale’s earnings.
Without the Northstar licensing charges, normalized EBITDA would have been approximately $2.1 million higher over the buyer’s forecast period.
If Vale still owned the sixteen designs outright, bankers estimated equity value could plausibly rise by $11 million to $17 million, depending on the multiple and how Alder Crown valued the heritage portfolio.
Dacre’s inheritance was being pressured from two sides.
Sophronia claimed he owed the estate millions in old advances.
At the same time, she had helped move valuable company assets into an entity she personally owned before the estate sold its controlling shares.
Dacre would receive less from a lower estate valuation.
Sophronia would recover some of the missing value privately through Northstar.
Then investigators found a Christmas-week email.
Sophronia to Aster Grove:
Need sale closed before archive inventory. P-3 still locked. Should be irrelevant, but Edmund kept redundant ownership records there.
Aster Grove responded:
Do not access estate materials outside approved process. Our position assumes all transfer approvals valid.
Sophronia:
Understood.
Three days later, at Christmas dinner, she slapped Aurelia.
Then kicked the rocking horse.
The reason for her panic was becoming almost embarrassingly specific.
She knew P-3 existed.
She knew the key was missing.
She knew Edmund used handmade objects as hiding places.
And she knew independent inventory was scheduled before the Alder Crown closing.
Dacre looked at Rebecca.
“She wasn’t looking for an inheritance.”
Rebecca shook her head.
“No.”
“She was looking for the cabinet.”
“Yes.”
“And the cabinet was looking backward.”
May you like



Rebecca understood.
“It could prove what she moved before anyone sold what remained.”







