Chapter 4
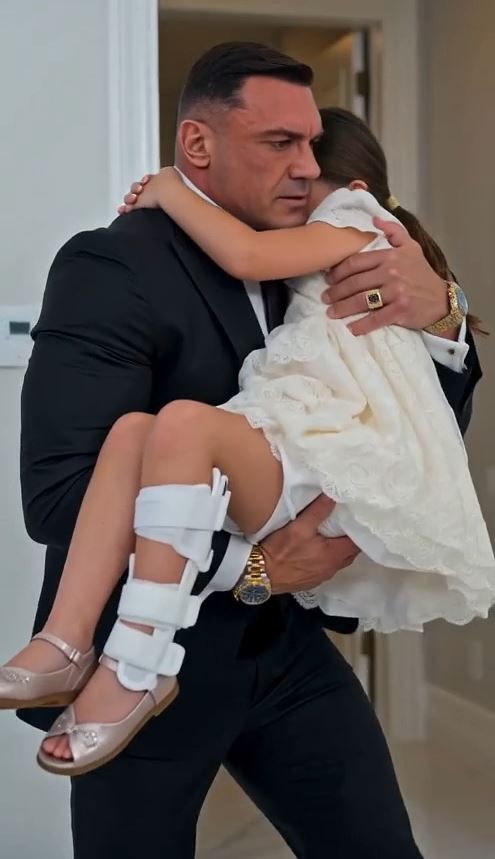
The insurer had made a settlement proposal two months earlier.
$2.4 million placed into a court-supervised structure for Isolde’s benefit, plus coverage of already approved medical expenses.
Isolde’s attorney rejected it as premature.
Not necessarily too low forever.
Premature.
They did not yet know the long-term nerve prognosis, whether surgery would be recommended, or how much assistance Isolde would need during adolescence.
The insurer’s own reserve was substantially higher.
That was normal.
Insurance reserves reflected risk, not guaranteed payout.
Then Meridian Lodging’s purchase agreement appeared in the investigation.
The buyer knew about Isolde’s accident.
It was disclosed.
The deal did not require the claim to vanish.
But it contained an indemnity provision.
If the claim remained unresolved above a negotiated threshold at closing, $12 million of sale proceeds would remain in escrow until liability and related disclosure issues were resolved.
Twelve million dollars would not bankrupt Corsetti Hospitality.
It would create real problems.
The company had planned to use much of the sale cash immediately to pay a maturing renovation loan on another hotel.
Holding back twelve million meant either:
Refinance at a higher rate.
Bring in an outside capital partner.
Sell another asset.
Or postpone renovations.
Loretta hated all four.
She had chaired Corsetti Hospitality’s family advisory board for almost twenty years.
She no longer ran daily operations, but people still treated her opinion as command.
Claudia’s incentive was different.
Her employment agreement included a $900,000 transaction bonus if the Meridian sale closed before year-end without a special indemnity escrow exceeding $5 million.
The bonus itself was lawful.
Common in major transactions.
It became relevant only if Claudia manipulated facts to protect it.
Then the insurer produced an email.
Claudia to claims counsel:
Home modifications appear temporary and family reports substantial functional improvement. We believe future-care model is overstated.
Claims counsel:
Please provide current physician support.
Claudia:
Home evaluation next week should clarify.
No current physician support existed.
Another email:
Brace may soon be discontinued.
That was also unsupported.
The orthopedist had written the opposite four days earlier:
Continue AFO. Gait instability remains significant with fatigue.
Claudia had received that note.
She simply did not send it to claims counsel.
Then Loretta wrote her:
If the child is still sleeping downstairs like an invalid, the planner will multiply every inconvenience by sixty years.
Claudia replied:
She is six. The calculation is more complicated than that.
Loretta:
Then make the facts simpler.
The phrase would later appear in three different investigations.
Make the facts simpler.
May you like



To Loretta, reality was not something observed.
It was something arranged before outsiders arrived.







