Chapter 3
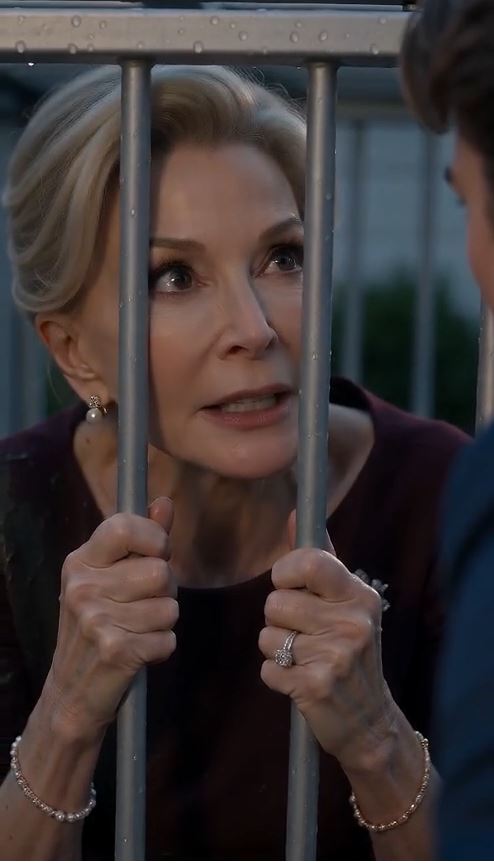
There was now a mortgage.
Or at least someone had tried very hard to create one.
Northfield Closing Services responded to a preservation demand immediately.
The silver-sedan visitor was a mobile notary named Caroline Reed.
She had been scheduled to witness Emma signing loan documents.
Borrower:
Tyler’s development company, Red Oak Properties LLC.
Guarantor:
Emma.
Collateral:
Emma’s residence.
Maximum secured amount:
$6.5 million.
Emma stared at the documents.
“I never agreed to this.”
The lender was Pilgrim Private Credit.
Not a criminal outfit.
A legitimate private lender specializing in distressed real estate.
Tyler’s company owned a stalled townhouse project.
Construction costs had risen.
A partner had withdrawn.
The senior bank required additional collateral before extending the maturity date.
Tyler offered his mother’s house.
The lender insisted on direct confirmation from Emma.
That was why Northfield sent a mobile notary.
Caroline Reed’s statement became critical.
“When I arrived, Mr. Tyler met me outside.”
“What did he say?”
“That Mrs. Emma wasn’t feeling well.”
“Did you see her?”
“For maybe thirty seconds.”
Emma had appeared at the hallway entrance.
Caroline greeted her.
Emma said:
“I’m not signing anything.”
Tyler immediately said his mother was tired and confused.
Caroline stopped the appointment.
Exactly what she should have done.
She left without notarizing anything.
Tyler called Northfield seven minutes later asking to reschedule for the following morning.
He said Emma would be “clearer after rest.”
That wording bothered investigators.
Then Pilgrim produced its underwriting file.
It contained a recent video of Emma.
She sat in her library.
Hair done.
Pearls.
Calm.
The video was dated five weeks earlier.
A lawyer asked:
“Do you understand Tyler is seeking financing for Red Oak Properties?”
Emma:
“Yes.”
“Do you understand your residence may be offered as collateral?”
Emma hesitated.
Then:
“I understand what he is proposing.”
“Do you consent?”
Before Emma answered, the clip ended.
The lender had rejected that video as incomplete.
They demanded a new one.
Emma watched the recording at the hospital.
“I remember that.”
Michael leaned forward.
“What happened?”
“Tyler told me he needed proof I understood his business situation.”
“Did you consent to the mortgage?”
“No.”
“Why were you recording anything?”
“He said the lender needed to know I wasn’t senile.”
Michael looked toward the detective.
There was the word again.
Senile.
Because another set of records was saying something very different.
The Hawthorne Family Support Trust—created by Emma’s late husband—had been reimbursing Tyler for in-home caregiving.
Monthly amount:
$12,500.
According to Tyler’s submissions, Emma suffered:
Significant memory impairment.
Frequent confusion.
Difficulty managing medication.
High wandering risk.
Inability to safely handle complex finances alone.
Michael stared.
“He told the trust she was impaired.”
“Yes.”
“And told the lender she was competent enough to mortgage the house.”
The investigator nodded.
Two versions of Emma.
One woman.
May you like



Two financial purposes.
The contradiction was only beginning.







